
We may earn money or products from the companies mentioned in this post.
Reviewed 24 October 2026. This guide is general education, not personal investment or tax advice. Prices can fall, selling can take time, and fees can turn an apparent gain into a loss.
How to invest in wine: the short answer
First decide whether you can tolerate an illiquid investment and ongoing costs. Then compare buying routes, check exactly what you will own, evaluate the particular wine and its price, arrange suitable storage, and work out how you could sell before buying. A famous label, a high critic score, or an attractive historical chart is not enough.
Your first useful task: build a one-page purchase file containing the all-in cost, ownership evidence, storage arrangements, and a realistic route to resale. This guide shows you what goes in it.
Fine wine offers something a stock portfolio does not: ownership of a physical collectible. That brings additional work. Someone must authenticate it, store it, insure it, keep the records, find a buyer, and settle the sale. A managed service can handle some of that work, but you still need to understand the contract and the bill.
1. Decide whether wine investing fits your needs
Start with the money, not the bottle. Can you leave it invested for years, continue paying storage and other charges, and tolerate receiving less than you put in? A long holding period creates more time for a sale, but it does not guarantee appreciation.
Pause before buying if the money is needed for an emergency, a near-term purchase, or essential expenses. Also pause if you would need a guaranteed sale date, cannot explain the ownership arrangement, or are relying on advertised returns to make the fees affordable. Learning about wine without investing is a perfectly useful outcome.
Four questions that shape your research
- Budget: how much can you commit after allowing for buying, holding, and selling costs? An account minimum is not a complete budget.
- Involvement: do you want to choose individual bottles, or assess a manager who chooses them? Either route requires diligence.
- Time and flexibility: could you wait beyond your preferred exit date? A service’s estimated sale time is not a promise.
- Purpose: are you collecting to drink, seeking financial exposure, or doing both? The best drinking purchase need not have an attractive resale market.
Use these answers to choose the next lesson, not to generate an automatic investment recommendation. If the terminology is new, start with the four questions above and take the steps in order.
What counts as investment wine?
Most wine is bought to drink. An investment case needs more: identifiable stock, credible provenance, a plausible secondary market, and a purchase price that leaves room for costs. Scarcity helps only when buyers want that particular wine. An excellent bottle can still be a poor financial purchase.
Market indexes can provide context, but they do not represent the return on your account. For example, the Liv-ex index page, checked on 24 October 2026, displayed a positive one-year change and a negative five-year change for its broad Fine Wine 1000. That is a useful reminder to examine more than one time window. An index also cannot tell you your own purchase markup, storage bill, selling costs, or tax liability.
2. Compare the main ways to invest in wine
Choose the ownership structure before choosing a brand. Buying bottles, owning an interest in a vehicle, and owning shares in a drinks business create different rights and risks.
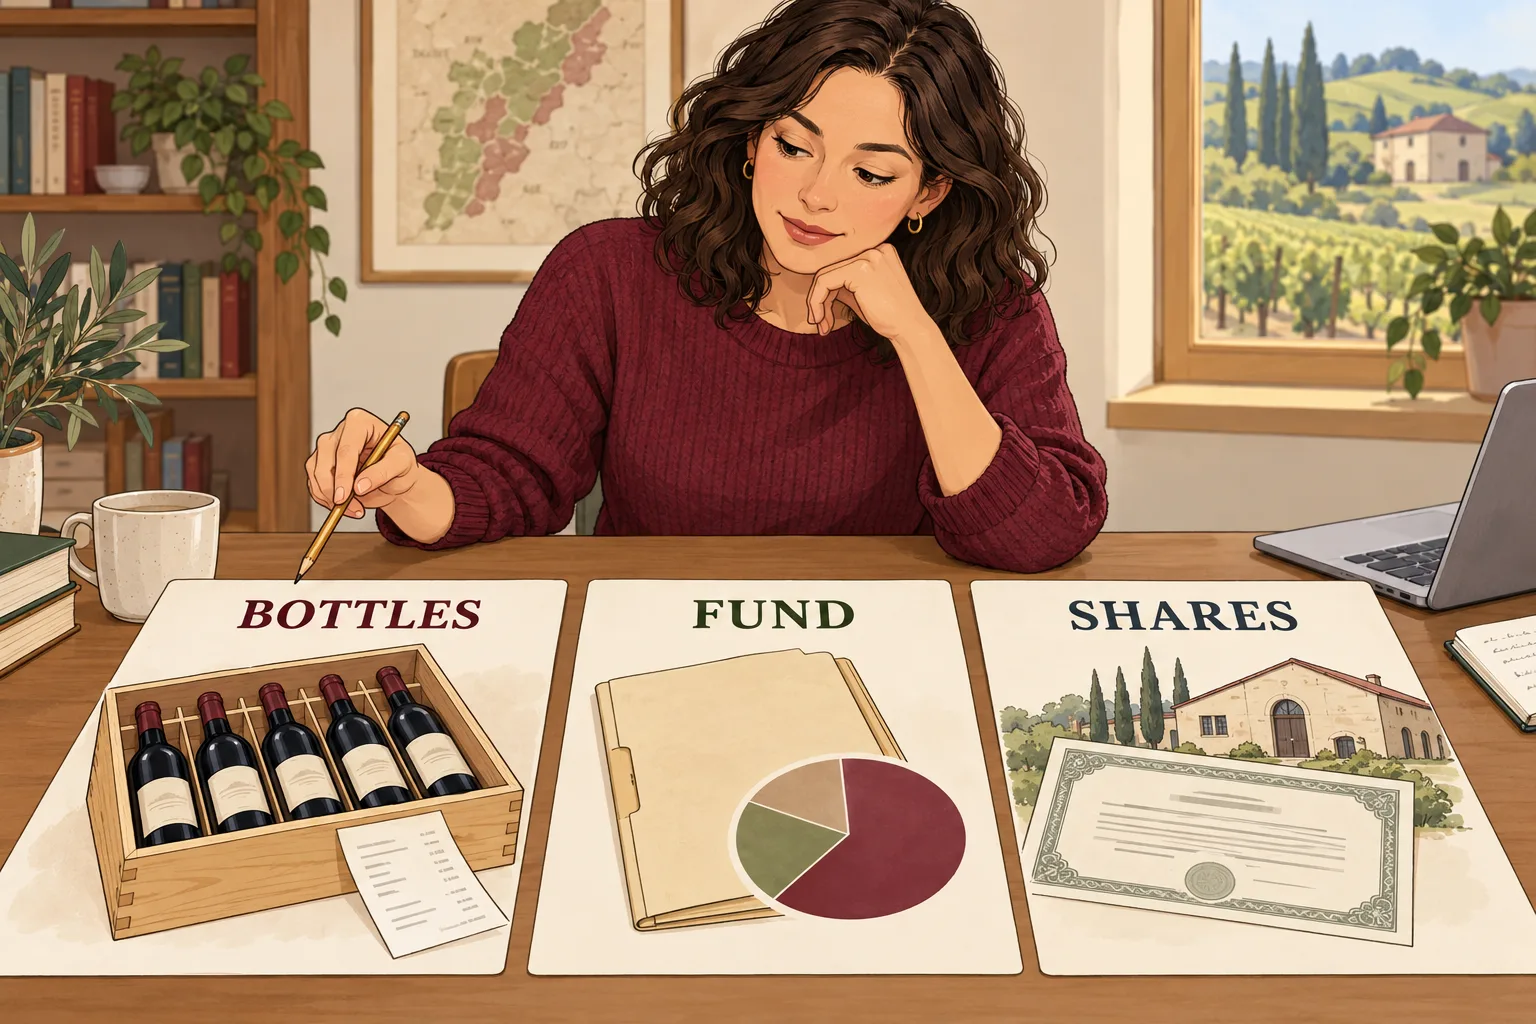
| Route | What you need to understand | Main diligence question |
|---|---|---|
| Managed physical-wine service | A manager selects wine and arranges services under its contract. | Which bottles are allocated to you, what evidence establishes ownership, and what happens if the operator fails? |
| Merchant or self-directed marketplace | You select particular bottles or cases; storage and resale may be separate services. | Is the stock available, fairly priced, and acceptable to the storage and resale routes you intend to use? |
| Auction | You buy a specific lot under the auction’s condition reports and sale terms. | What is the total after buyer’s premium, taxes, handling, and transport, and what recourse exists for problems? |
| Fund, syndicate, or fractional interest | You may own an interest in a legal vehicle rather than title to particular bottles. | Who controls sale timing, what distributions and transfer rights exist, and can you exit independently? |
| Wine-related company shares | You own business exposure, not a claim on the appreciation of a particular case. | Do you understand the company’s wider operations, debt, valuation, and equity-market risks? |
For managed services and merchants, use our wine investment company comparison. It separates published terms from questions that still need an answer. Our Vinovest review provides a closer look at one provider, including the distinction between managed and trading services.
What does “in bond” mean?
In the UK wine trade, in-bond stock is stored in an approved bonded warehouse without duty and VAT having been paid. Taking delivery can trigger those charges. This is a storage and tax status, not a guarantee of quality, a tax exemption on investment gains, or proof that the seller owns the wine. Berry Bros. & Rudd explains its in-bond storage arrangements; other countries and providers can have different rules.
Be careful with wine sold before delivery
An en-primeur or futures offer can involve paying before the wine is physically delivered. Establish what exists now, when delivery is due, who must deliver, and what happens if they do not. Compare the total offer with already-bottled alternatives rather than assuming an early release must be cheaper.
3. Build a budget that includes the whole journey
The bottle price is only the first line. Get a written schedule for purchase commissions or markups, storage, insurance, management, transfers, selling, currency conversion, and delivery. Some services bundle charges; others bill them separately. Avoid adding storage twice when it is already included, or leaving it out because the headline says “no trading fee.”
Ask how each percentage is calculated. A fee on current market value differs from a fee on original purchase cost. A monthly calculation can differ from a simple annual deduction. A minimum charge per case can matter more than the headline rate on a small holding.
Worked example: the wine rises, but the investor loses
This UK-trade illustration uses British pounds (GBP). The figures are invented, not a provider’s prices, a US cost quote, or a return forecast.
- Wine purchase: £3,000.
- Purchase and transfer charges: £100.
- Storage and insurance: £100 a year for five years, paid separately, totaling £500.
- Total cash spent: £3,600.
- Sale price after five years: £4,000.
- Hypothetical selling commission: 10%, or £400; final handling: £50.
- Cash received: £3,550. Overall result: £50 loss before tax.
The wine’s price rose by a third, but the costs absorbed the gain. Under these assumptions, the break-even sale price is (£3,600 + £50) ÷ 0.90 = about £4,056. That excludes inflation, currency changes, and tax.
Run a falling-price and flat-price case as well as an optimistic one. Our wine investment cost guide provides a fuller worksheet. A scenario is useful because it exposes assumptions; it does not predict the market.
4. Evaluate the exact wine, not just the producer
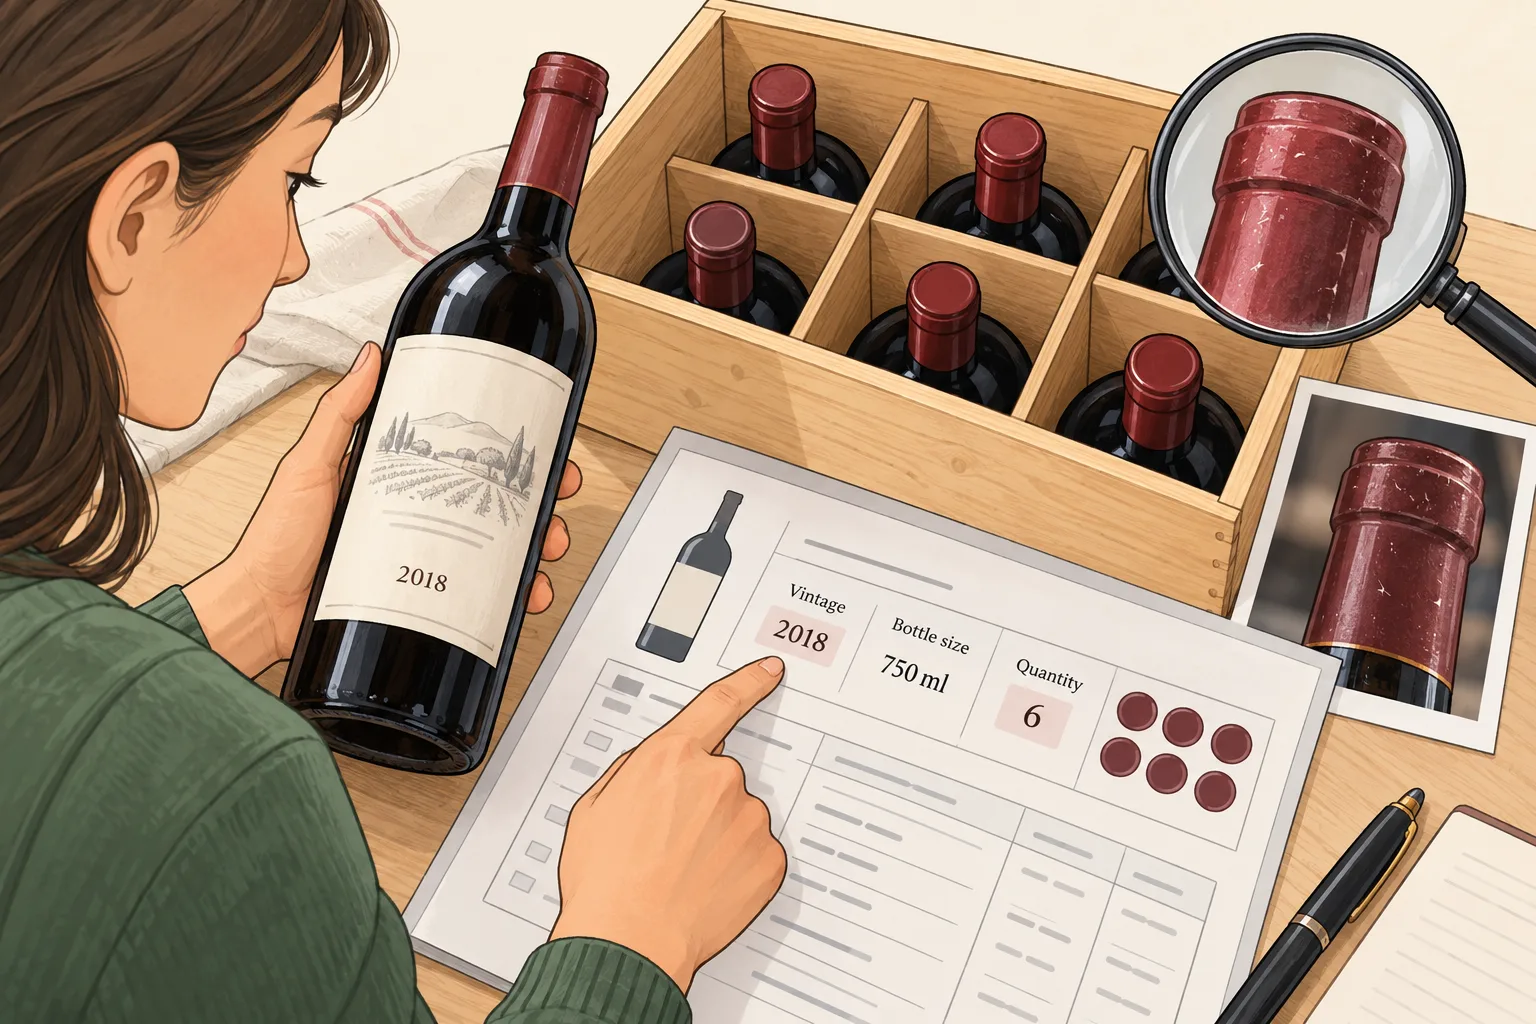
“Buy Lafite because it is Lafite” skips the important questions. Producer, wine or cuvée, vintage, bottle size, case quantity, packaging, condition, location, and tax status all matter. A listing for six bottles cannot be compared directly with a twelve-bottle case, and a retail asking price does not establish what a seller will receive.
- Match the stock. Write down the full identity and compare like with like, including fees and currency.
- Look for evidence of demand. Check dated completed sales and realistic bids where available. Ask whether more than one buyer or resale route is plausible.
- Compare the price. Separate merchant asking prices, auction hammer prices, auction totals, and net seller proceeds. Record the source and date.
- Read the condition evidence. Review bottle levels, labels, capsules, packaging, photographs, and storage records. Images help, but do not by themselves prove authenticity.
- Test the story. A critic score, small production run, or famous name does not establish a profitable exit price.
- Price the friction. Repeat the cost calculation using the exact offer, not a generic fee estimate.
Wine-Searcher can help locate advertised offers. Auction results and a merchant’s current purchase quote answer different questions. Use those distinctions to record what each price actually represents.
For examples across Bordeaux, Burgundy, Champagne, Italy, and the New World, see what to look for in investment wine. Treat the names there as research starting points, not a shopping list.
5. Verify ownership, custody, and insurance
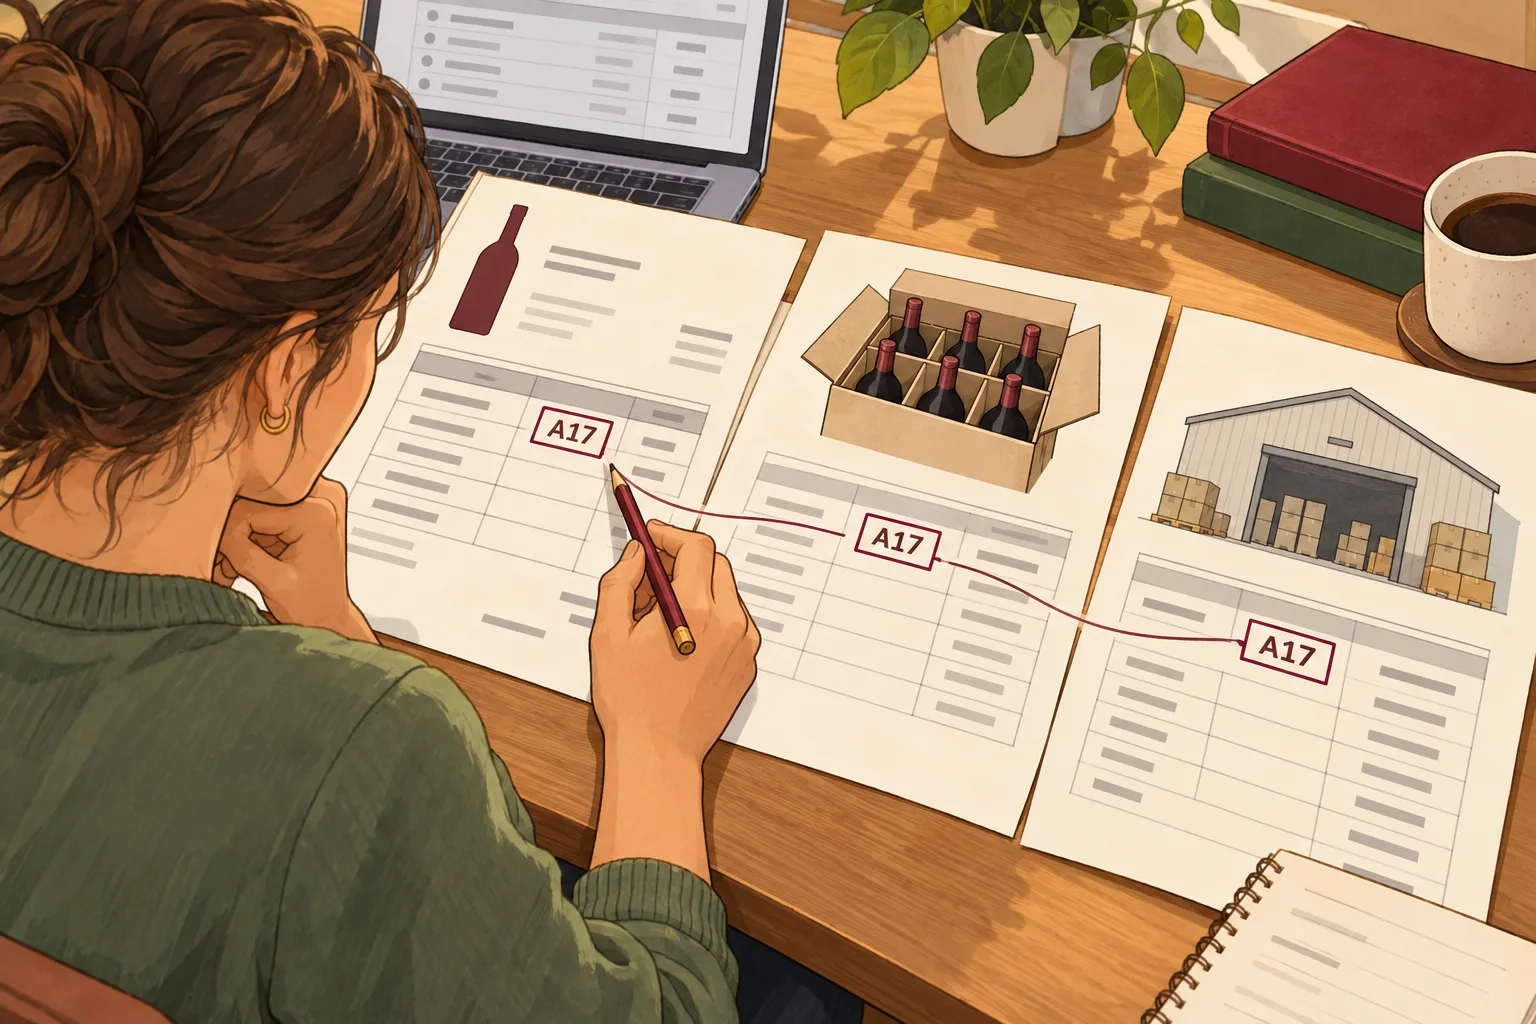
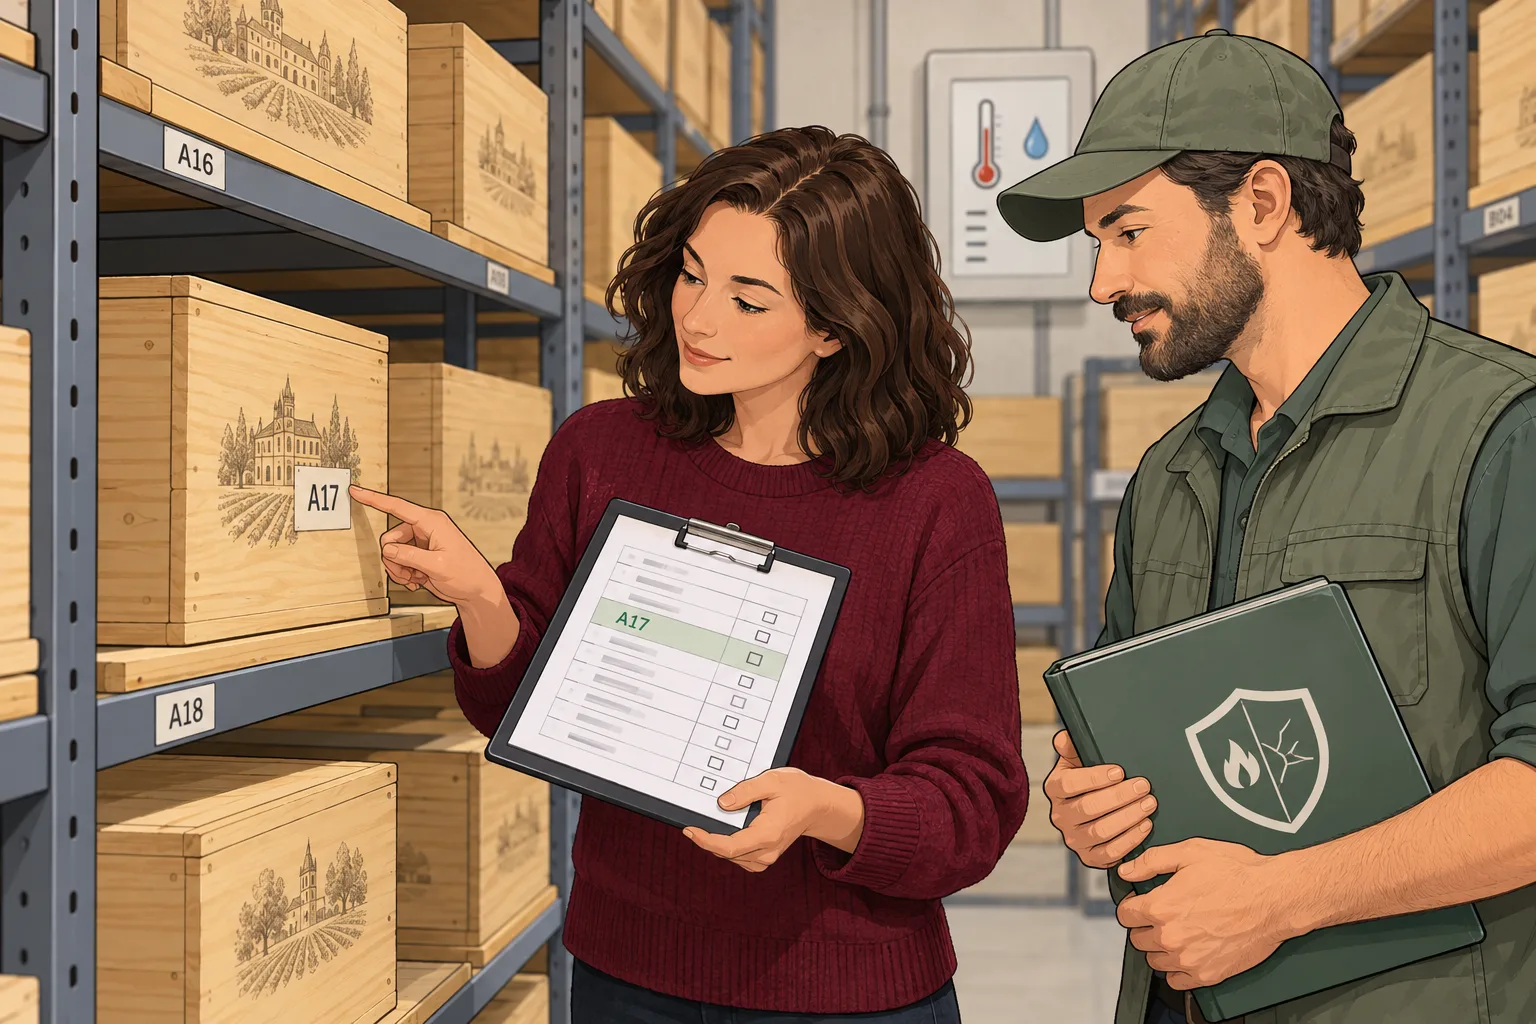
Before funding an account, get four answers in writing: who owns the wine; where it is held; what records identify it; and how it can be transferred or sold. A dashboard, a certificate, or a reassuring logo is not a substitute for understanding the contract.
| Evidence | What to check |
|---|---|
| Invoice and contract | Correct legal entities, the exact wine, price, charges, payment status, and when title passes. |
| Inventory or allocation record | Vintage, bottle size, quantity, case or stock identifiers, and whether stock has actually been allocated. |
| Warehouse confirmation | Named facility, account or custody arrangement, record access, and the process for independent confirmation where available. |
| Insurance explanation | Who is insured, what valuation basis applies, exclusions, excesses, and who makes a claim. Market-price declines are not the same as physical damage. |
| Transfer and failure provisions | Who can release stock, transfer fees, any liens or unpaid charges, and the process if the operator stops trading. Obtain legal advice if ownership protections are unclear. |
Professional storage can protect condition and preserve a custody record. It does not remove fraud, market, or counterparty risk. A home-stored bottle is not automatically worthless, but future buyers may require more evidence and some resale services may not accept it. Check acceptance rules before moving wine.
Use the checklist above to compare facilities and questions. Keep copies of invoices and inventory records somewhere you can access independently of the provider’s app.
6. Plan the exit before buying
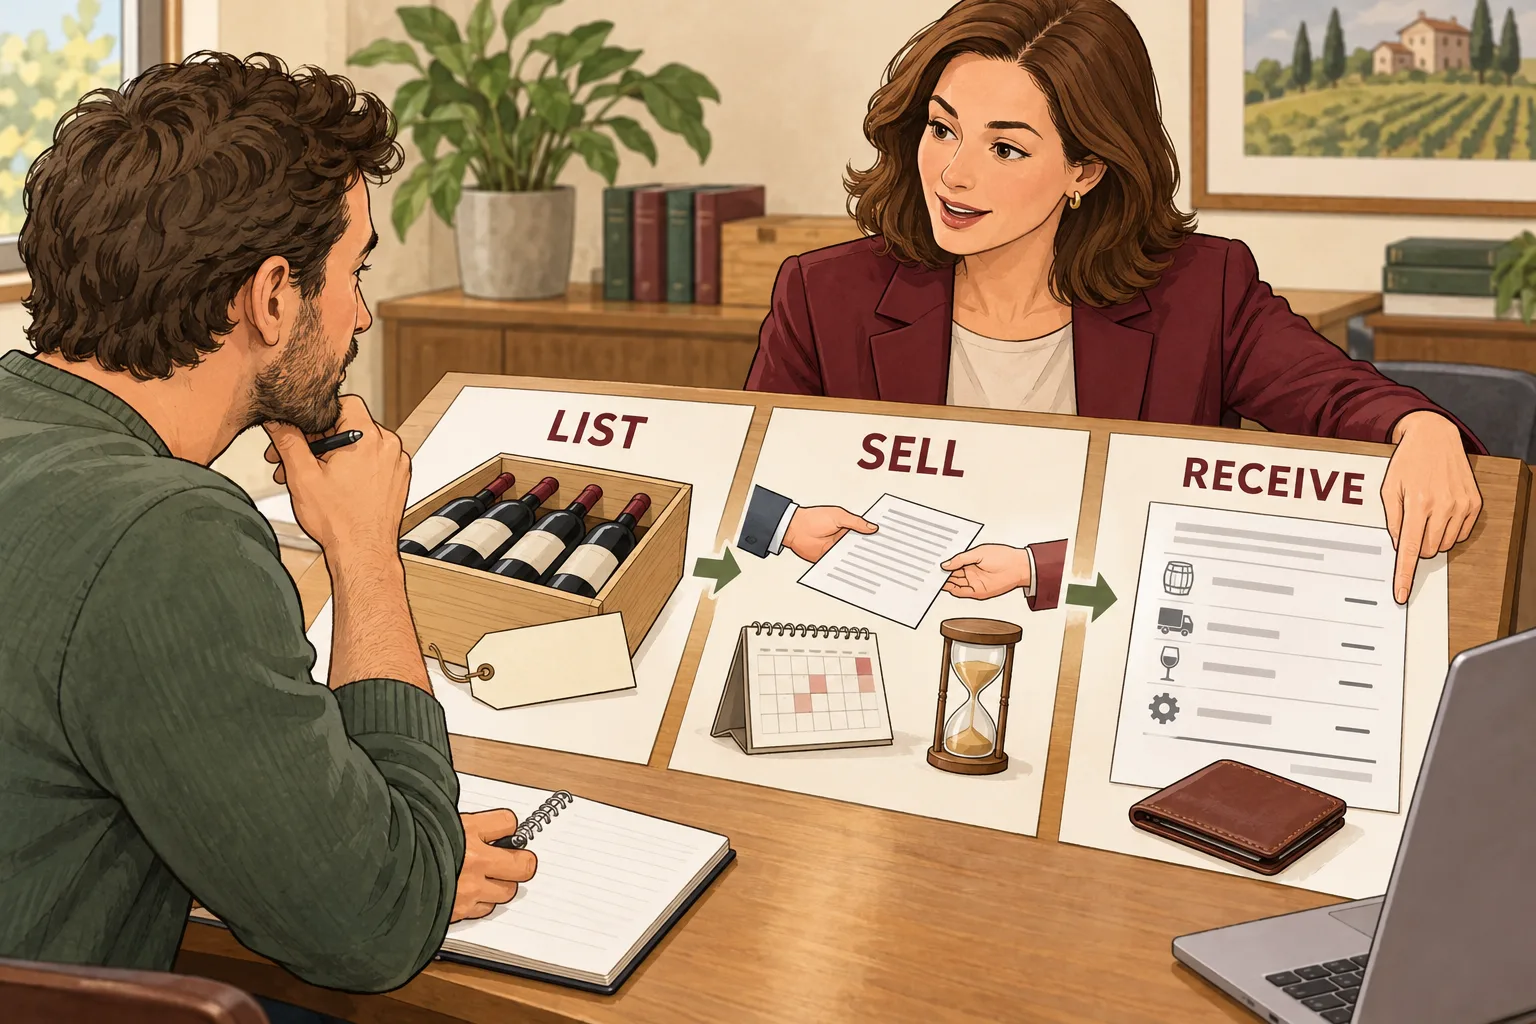
Ask the seller to explain a hypothetical sale of the exact stock you intend to buy. Does the service purchase it outright, list it for other customers, broker it to the trade, or consign it to an auction? A listing is not a completed sale, and a displayed valuation is not a guaranteed bid.
- Eligibility: will the intended resale route accept the bottles, packaging, condition, and storage history?
- Price: who sets it, can you set a reserve, and may a discount be needed?
- Costs: what commissions, early-exit charges, inspections, transfers, and taxes might apply?
- Timing: separate time to find a buyer, delivery or inspection, settlement, and withdrawal of cash.
- Fallback: can you transfer to another merchant or warehouse? What would that cost, and could it take longer?
Request a written net-proceeds estimate, not just an optimistic future valuation. Do not assume that taking the bottles home is a cost-free alternative: transport, insurance, duties, taxes, and alcohol-delivery restrictions may apply.
7. Keep records and check the tax rules
Save purchase and sale invoices, fees, storage statements, currency conversions, and ownership records. Your tax residence, the location of the wine, the legal structure, and whether you trade as a business can all matter. A provider’s general tax statement does not settle your own treatment.
United Kingdom: HMRC’s guidance on wines and spirits discusses chattels and wasting-asset exemptions, including circumstances in which bottles form a set. Do not assume every fine-wine gain is tax-free.
United States: the IRS capital-gains guidance states that net long-term gains from collectibles can face a maximum 28% rate. That is a maximum for this category of long-term gains, not a flat rate applying to everyone; short-term gains are generally taxed as ordinary income. Ask a qualified adviser about the treatment of your wine or investment vehicle, deductible costs, and any additional taxes.
8. A practical first-purchase checklist
Complete this before transferring money. If an essential answer is missing, the next step is more research, not a larger deposit.
- I can explain why I am considering wine, the money I can risk, and the costs I can continue paying.
- I understand whether I own bottles, an interest in a vehicle, or shares in a business.
- I have matched the exact wine and compared dated, like-for-like prices.
- I have the complete fee schedule and a downside, flat-price, and upside calculation.
- I can identify the seller, custodian, storage location, and documents supporting ownership.
- I have checked insurance coverage, exclusions, and claims arrangements.
- I understand the expected sale process, charges, settlement, and transfer options.
- I have recorded unresolved questions and obtained tax or legal help where necessary.
Warning signs worth taking seriously
Be wary of guaranteed returns, pressure to act immediately, unexplained markups, unverifiable stock, or promises that the firm earns nothing until you profit. Independently verify the seller, the stock, and the price rather than relying on a certificate or a sales call. The existence of wine alone does not make the purchase fairly priced or safe.
Frequently asked questions
How much money do I need to start?
There is no universal minimum. Start with the current minimum for the route you are considering, then add its buying, holding, and exit costs. A small budget can be particularly affected by fixed charges and limited diversification. Compare the full cost of ownership, not just the deposit.
Can I invest without choosing individual bottles?
Managed services and some investment vehicles make selections for you. You still need to assess their fees, incentives, ownership arrangements, custody, valuation, and exit provisions. Delegating selection does not eliminate diligence.
Does wine always get more valuable as it ages?
No. Demand can weaken, purchase prices can be too high, condition can deteriorate, and costs continue. A longer holding period can add storage expense without producing a profitable sale.
Is an advertised return comparable with my net return?
Only after checking what it measures. Ask whether it is an index, selected transactions, a model, or actual customer outcomes; whether fees and currency effects are included; and whether gains were realized. Your relevant result is cash received minus all cash spent, with the timing and tax treatment considered separately.
Choose your next step
- Still deciding: revisit the suitability questions.
- Testing affordability: complete the cost worksheet.
- Comparing services: use the company comparison and Vinovest review.
- Evaluating an offer: work through wine selection, valuation, and storage checks.
Sources were checked on 24 October 2026. Provider terms and tax rules can change. This article does not verify any individual seller, bottle, or investment offer and does not promise a return.
Pingback: How Much Does It Cost to Invest in Wine? Fees Beyond the Bottle – Wine Asset Guide
Pingback: Best Wine to Buy for Investment: What Beginners Should Look For – Wine Asset Guide
Pingback: Vinovest Review 2026: Fees, Ownership and Exit Risks – Wine Asset Guide
Pingback: Best Wine Investment Companies: 5 Models Compared for 2026 – Wine Asset Guide